

Still Dancing
Welcome to issue #38 of The Davem Dish. Every week I share what actually works in investing based on my 20 years of wins, losses and expensive lessons. You’ll also get my thoughts on solopreneurship and life in general because the same principles apply — keep it simple, stay consistent and focus on what matters.
Every August, a few dozen money managers, economists, and market veterans — aka the “professionals” — disappear into the Maine woods for an invite-only fishing trip called Camp Kotok. David Kotok started it about twenty-five years ago in a tiny town called Grand Lake Stream, and it runs under the Chatham House rule, which means attendees can talk about what got discussed but not who said it. One camper calls it the Walden woods for Wall Street.
The thing everybody was anxious about this year was AI.
You don’t have to attend an exclusive finance camp to have this same concern. It’s the same one talked about at the neighborhood barbeque, on the seventh tee, and at the end of your local bar. Is this sustainable and what happens to my 401(k) if it blows up? The difference between those conversations and the ones in Maine are the camp attendees manage other’s money for a living, which as we’ll get to makes them less free to act than you are.
The worry wasn’t the technology. Campers swapped notes on the agentic tools they’ve wired into their own workflows. All agreed it made their lives easier and is likely to get better. The real worry was the money.
Big tech companies that used to have untouchable balance sheets are running cash flow negative, and the spending that never shows up on a balance sheet is bigger still. The bond market is trying to digest a quarter-trillion dollar wave of AI debt. Gross U.S. debt just crossed $40 trillion for the first time. And the country’s growth rate is increasingly propped up by the investment boom itself, which is a nice way of saying the buildout is now holding up the economy that’s supposed to justify the buildout.
Halfway through a talk on AI research, one of the speakers — a longtime tech investor — was asked the only question that matters: all this spending, will there be a return on it? His answer was that he couldn’t tell them, that Wall Street couldn’t tell them either, and that it worried him.
Adam Phillips, who runs investments at EP Wealth Advisors, put it about as plainly as anyone can. Everybody’s in the same boat, the experts don’t know, and it’s unsettling.
Some talked about rotating into other corners of the S&P 500 and a few had trimmed their large-cap tech positions, but essentially nobody was betting against it. They were all still long. The tech investor who couldn’t answer the return question closed with this, “when the music stops, someone’s going to be holding the bag.”
We’ve Heard This Before
On July 9, 2007, with credit markets already showing cracks, Citigroup CEO Chuck Prince sat down with the Financial Times and dismissed the idea that the cheap-credit buyout boom was ending. Liquidity was too deep, he said and Citi wasn’t pulling back. Then came the line that outlived his career, “as long as the music is playing, you’ve got to get up and dance.”
Prince was out four months later, in November 2007. Citigroup needed a government rescue the following year. The quote became shorthand for an industry that didn’t see what was coming.
I’m not going to defend a bank CEO, who was more than well compensated during his tenure, but that reading was a bit unfair. Prince wasn’t claiming he couldn’t see it. What he was describing was a constraint. If his competitors kept underwriting and he stepped back, Citi underperforms for however many quarters the party runs, and he’s gone long before he’s proven right. Any other bank CEO in the same position would have done the same thing.
Nineteen years later, a room full of people at a fishing cabin are reaching for the same metaphor about a different asset. Keynes described this back in 1936. For a professional, failing conventionally is safer than succeeding unconventionally. Lose money the same way everyone else lost it and you keep your job. Sit out a two-year run and you never get to be right in year three, because you won’t be there.
That’s career risk, and I wrote about it back in Part I of the Deprogramming Series as one of the structural handcuffs on professional money managers, right alongside redemption pressure, and red tape. It’s why crowded trades stay crowded long past the point where the people in them believe the story.
The Constraint You Don’t Have
None of that applies to you.
Nobody redeems your capital because you trailed the benchmark for three quarters. No committee asks why you’re underweight the popular names. No board reviews your numbers. A big force distorting professional behavior simply isn’t in your account, and most individual investors never think to use it.
Using it doesn’t mean selling everything and sitting in cash. That’s just another prediction that usually costs you money. Jeremy Grantham has been making the sell-everything case for years now, and I’ve covered the receipts on those claims. The market roughly doubled after his 2021 call.
What it means is deciding now, while nothing is happening, instead of during the week — whenever that might be — when everything does.
Know what you actually own. This has been well documented but is worth repeating. Your S&P 500 index fund is not diversified. The ten largest companies in the S&P 500 make up somewhere around 40% of the index depending on the day, up from around 19% a decade ago. NVIDIA alone is close to 8%. Add Apple, Microsoft, Alphabet, and Amazon and you’re over a quarter of the entire index in five companies — all companies heavily exposed to the AI trade.
And that trade has spread well beyond the tech companies. It includes the utilities building generation capacity, industrial companies doing the electrical work and chip and fiber companies filling up the data center racks. You can be a lot less diversified than your brokerage account pie chart claims.
So do the math. Add your index funds, your target-date fund, your company stock if you have any, and your individual positions. Then figure out what percentage of the total rides on the AI story continuing.
Your age matters. This matters more than your opinion about whether AI is a bubble. The two big drawdowns of this century show you what a bad one looks like. In the dot-com bust the S&P 500 fell around 49% from peak to trough. In the financial crisis it fell about 57%.
A simple visual:
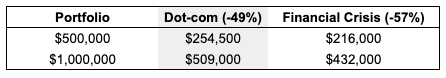
If that doesn’t grab your attention, the recovery math will. Down 49%, takes a 96% gain to break even. Down 57% takes 131%. And the clock can be unforgiving. If you bought at the March 2000 dot-com peak, it took you thirteen years to become whole again, with another market meltdown in the middle of that period.
If you’re 60 and planning to retire in the next few years, this scenario is terrifying. You’ve likely made a lot of money since the March 2009 bottom — the S&P 500 is up tenfold. You may also have gotten used to the higher than normal average annual returns over the last ten years (~15%). So the thought of losing half your portfolio value, at the same time you want to start drawing from it, leaves a pit in your stomach. The good news is there’s a very simple way to give yourself peace of mind without selling it all. Just reduce your exposure and rebalance. If you see your retirement portfolio is 100%, 90% or even 80% in stocks, lower it by 20% and move the cash to a money market account. You’re taking chips off the table. If the market continues going up, you’ll still experience the gains and if it goes down big, you won’t lose half of your money and be kicking yourself for being greedy and not acting sooner. Nobody at the fishing camp can locate the top, and neither can you.
If you’re 35, of course a meltdown wouldn’t feel good and would affect the entire economy, but you don’t have to worry that much from an investing perspective. You have time on your side. Keep the automatic contributions running regardless if the market is going up or down. Dollar cost averaging doesn’t work if you stop contributing when the market is down. And look at any big downturn as a sale — times when quality companies finally trade at prices where the math works. But only if you already have a valuation process in place. Building one during a market panic doesn’t work.
Don’t gamble. The temptation in any bull market is what you see propagated on your feed everyday. Options plays, buying on margin, 2x and 3x leveraged ETFs on whatever was hot last month, somebody’s screenshot of turning $10,000 into a million. The pitch is the same — if you’re right, why settle for boring returns. Speculation and leverage isn’t new but the scale is. U.S. options volume hit a record 73 million contracts a day last quarter, with almost 28% expiring the same day. Leveraged ETF assets hit a record near $200 billion, up from roughly $30 billion in 2009. Margin debt hit a record $1.53 trillion in June. Are you seeing a pattern here?
Two blowups this summer give a glimpse into what speculation and leverage does. The “Nostradamus of AI” himself, Leopold Aschenbrenner, lost $35 billion in a few weeks — and was forced to sell his book at a discount — when his highly leveraged positions dipped in July. In Korea, retail investors poured roughly $9.7 billion into new single-stock leveraged ETFs on Samsung and SK Hynix in a matter of weeks. The chip ETFs then fell 70% to 80% from their highs and the finance minister ended up apologizing to parliament.
The thing was neither of these events were precipitated by a crash, just an ordinary pullback in a bull market. The S&P 500 is near an all-time high. The KOSPI (Korea’s version of the S&P 500) has already rebounded 20% off its July low. The indexes came back but the people liquidated on the pullback probably didn’t. And that’s what leverage does. It doesn’t just amplify your losses, it removes your ability to wait, which is an advantage you have over the professionals.
Choose your own deadline. You can’t eliminate uncertainty but you can protect yourself in any scenario. Rebalance, use trailing stops on positions that have run (even ETFs), and a hard loss cap on everything else. The percentages are a personal decision, but don’t negotiate with them. There isn’t a magic number. The point is that decisions get made by the calm version of you rather than the one refreshing a chart at noon on a down day after a down week. If a single position falling in half would genuinely alter your plans, it’s too big, regardless of how good you think the company (or the index) is.
None of this requires an answer to the AI return question and it doesn’t require you to nail a bold prediction. That’s the whole point. The professionals have to keep dancing to stay employed. You get to decide, in advance, exactly when you walk off the floor.
The music is still playing. Just know where your chair is.
Cheers,
Andrew
If you’re concerned about your AI exposure and what to do next, that’s what the Davem Investor Audit is for. Ninety minutes, your actual portfolio and timeline. We work out what your real exposure is, what a big drawdown would do to your plans, and what decisions you could consider making now.
Learn more about The Davem Investor Audit here.
Thanks for reading The Davem Dish! If you enjoyed this issue, feel free to subscribe and share it with other awesome people like you.
The content provided are personal opinions and presented for educational purposes only, as of the date published or indicated. Davem Advisors LLC is not a bank, licensed securities dealer, broker or investment advisor. Displayed returns are unaudited. Nothing stated constitutes a recommendation or advice as to whether any investment is suitable for a particular investor. You alone are solely responsible for determining whether any investment, strategy or service is appropriate for your objectives. Past performance is no guarantee of future results. Inherent in any investment is the risk of loss.